
Related News
- 00
0000-00
How to calculate crawler excavator lifecycle cost per operating hour - 00
0000-00
Hitachi Introduces ZX180W-7 and ZX220W-7 Wheeled Excavators to North America - 00
0000-00
How order volume affects private label equipment production costs - 00
0000-00
Volvo Group Plans Dedicated Mining Entity for Equipment and Autonomous Solutions - 00
0000-00
How much does a 3D grader guidance system cost fully installed?
A lower purchase price can still produce a higher cost per operating hour. When comparing crawler excavators, lifecycle cost depends on how much the machine costs to own and operate, how many hours it actually works, and what it is worth when you sell it. A cheaper machine can lose its advantage through fuel consumption, undercarriage wear, repair delays, or weak resale value.
The basic calculation is straightforward: divide total net ownership and operating costs over the planned holding period by realistic lifetime operating hours. The difficult part is keeping the cost boundaries and hour definitions consistent. An attractive hourly figure is useful only when it reflects the work, ground conditions, and support arrangements the machine will actually face.
Start with a formula that keeps costs separate
For a practical, undiscounted comparison, use:
Lifecycle cost per operating hour = (Acquisition cost + Financing cost + Ownership overhead + Operating expenditure − Net resale proceeds) ÷ Total operating hours during ownership
Acquisition cost should reflect the machine as delivered and ready for the intended work. Include required buckets, couplers, auxiliary hydraulic provisions, delivery, commissioning, and any necessary control systems. Compare equivalent configurations; a lower quotation may exclude equipment included in another offer.
Operating expenditure covers fuel or electricity, scheduled maintenance, wear parts, repairs, and other expenses incurred while using the machine. Ownership overhead can include insurance, storage, registration where applicable, and recurring technology subscriptions. Net resale proceeds mean the expected sale price after selling fees, disposal transport, and any preparation costs.
Keep the calculation on one tax basis. Recoverable taxes generally do not belong in the economic cost comparison, although their timing may affect cash flow. Include taxes that remain a genuine expense.
Do not add depreciation when the calculation already includes acquisition cost minus resale proceeds. That difference already captures the machine’s loss in capital value. Adding accounting depreciation would count the same loss twice.
Define “operating hour” before comparing quotations
An engine-hour meter can record time spent idling, warming up, or waiting for trucks as well as digging. Productive hours describe time spent performing useful work. Scheduled hours describe the time the machine was intended to be available. These measures answer different questions.
For a conventional machine cost calculation, recorded engine hours provide a practical denominator, provided all offers use that same basis. For a project delivery decision, cost per productive hour or cost per unit of material moved may reveal more.
Use the following relationship when planning engine hours:
Expected engine hours = Scheduled hours − Hours lost while the engine is off
Those losses can include maintenance, breakdowns, weather interruptions, access restrictions, and gaps between projects. Avoid subtracting the same interruption under several categories. If historical annual engine hours already reflect these losses, applying another general availability reduction would understate utilization.
Build the forecast around the work pipeline. A machine assigned to recurring production work has a different utilization outlook from one purchased for intermittent contracts. Ownership costs continue during idle months, so optimistic annual hours can make an otherwise expensive purchase appear economical.
For battery-electric equipment, establish what the reported operating-hour counter measures. Use an equivalent working-time definition across powertrains, and include charging interruptions when they reduce achievable operating hours.
Build the cost sheet around the machine’s duty
A useful crawler excavator lifecycle cost model separates expenses by their cause. Some follow calendar time, some follow engine hours, and others depend heavily on ground conditions or the type of work.
Keep machine-only cost and fully staffed operating cost clearly labeled. If the decision requires operator wages, include them consistently, including paid waiting time where relevant. Site mobilization should also follow a stated rule: a frequently relocated excavator may incur substantial transport expense that a permanently assigned machine avoids.
Estimate energy from comparable work
Calculate fuel expenditure as expected engine hours multiplied by average fuel consumption per engine hour and delivered fuel price. The consumption assumption should represent the intended application. Trenching, bulk excavation, lifting, hammer operation, and frequent tracking place different demands on the machine.
Compare consumption figures measured over similar duties and with similar idle-time treatment. Lower hourly consumption does not automatically mean lower production cost: a machine that burns less fuel but takes longer to complete the work can consume more fuel per completed task.
For an electric excavator, calculate electricity cost from energy drawn at the charging point, including charging losses. Add applicable demand charges, charger installation, and site electrical work where these are attributable to the machine. Allocate shared infrastructure consistently. Include battery replacement only where the ownership plan and credible battery-life assumptions justify it.
Give undercarriage wear its own calculation
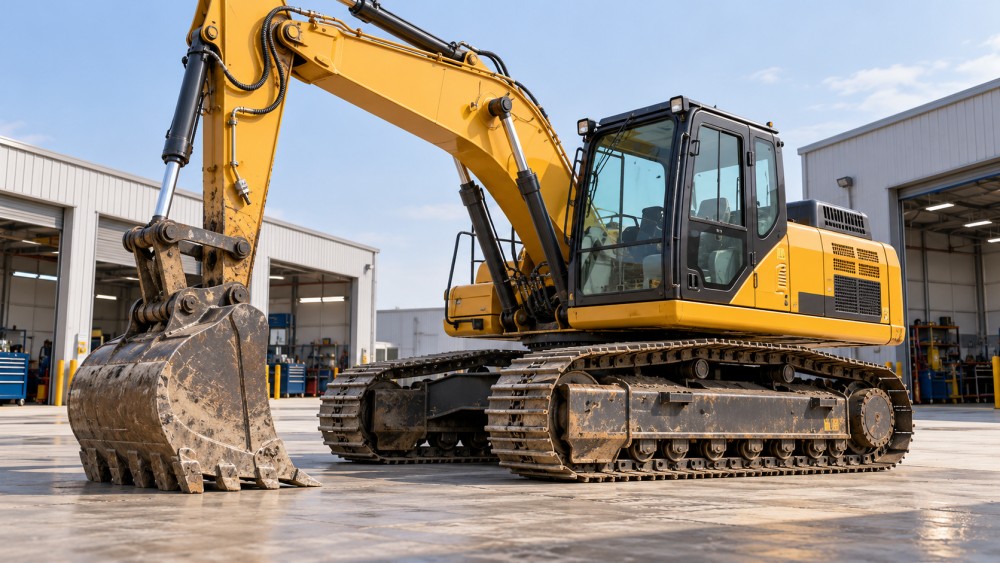
Tracks, chains, rollers, idlers, sprockets, and related labor deserve separate attention because wear depends strongly on the application. Abrasive material, extensive travel, turning practices, track tension, and packed debris can change the replacement pattern.
Estimate expenditure from the maintenance events expected during your holding period. A replacement-cost-divided-by-life allowance can help compare machines, but check it against when cash will actually be spent. Charging a full replacement near disposal while assuming the resale value of a machine with worn tracks creates an inconsistent result.
For a used excavator, establish remaining component life at purchase. Its first major wear expense may arrive much sooner than the same expense on a new machine. Condition inspection therefore affects the cost forecast directly.
Account for downtime without charging it twice
Downtime affects both expenditure and available hours, but it does not create the same cost on every job. A breakdown may require a replacement rental, paid standby labor, additional transport, or rescheduling. On another assignment, spare fleet capacity may absorb the interruption with little extra cash expenditure.
In the lifecycle calculation, include actual expected additional expenses and use realistic achievable hours. If breakdowns reduce engine hours while ownership costs remain unchanged, the hourly rate already rises. Adding a general “downtime cost” based on that same ownership rate can duplicate the effect.
Replacement hire requires particular care. If rental equipment maintains project output during a repair, its cost can be included in a broader service-delivery comparison. Clearly identify whether the denominator represents the owned excavator’s hours or the total hours delivered by owned and replacement equipment.
Lost production belongs in a separate project-impact assessment when it matters. An excavator feeding a crusher or supporting a constrained loading operation can affect other equipment and the completion schedule. That consequence may justify paying more for dependable support, but it should remain distinguishable from the excavator’s direct hourly cost.
Make financing, warranties, and resale assumptions consistent
If acquisition cost is included in full, add financing interest and relevant fees rather than the entire loan repayment stream. Loan principal repays the purchase price already counted. For cash purchases, an internal cost-of-capital allowance can be used, but it should follow the same policy across offers.
For a discounted analysis, model dated cash flows and apply a consistent discount rate. An equivalent hourly result requires a compatible treatment of operating hours; dividing discounted expenditure by an unrelated, undiscounted hour total can distort comparisons. Avoid mixing a simple ownership-cost model with selected discounted items.
Warranty coverage should reduce the specific repair expenses it covers. It does not eliminate wear, servicing, exclusions, or all costs associated with an interruption. Examine coverage limits, required maintenance, claim arrangements, field labor, travel charges, and responsibility for transporting a disabled machine.
Resale estimates should correspond to the forecast disposal age, hours, and condition. Specialized attachments may have a different buyer base from the carrier machine. Separate their residual values where appropriate, and distinguish a contractual buyback commitment from a seller’s informal estimate.
Compare supplier offers using the same operating scenario
Give each supplier the same application description: material, digging requirements, attachment use, travel intensity, shift pattern, annual hours, and planned holding period. Request the evidence behind fuel, maintenance, wear-life, and residual-value assumptions. A quoted hourly cost is difficult to assess when its underlying duty cycle remains undefined.
Use a common calculation sheet and keep supplier claims separate from assumptions you control. This makes it easier to identify whether an apparent advantage comes from equipment performance, omitted costs, or a more optimistic forecast.
The comparison should also reflect service capability. Parts availability, technician access, diagnostic support, and repair arrangements influence how quickly a failure becomes a return to work. Ask what support is included in the price and what attracts additional charges, particularly at remote sites.
Evaluate attachments and technology through the tasks they improve. Grade control may reduce checking time or rework where the workflow supports it. A quick coupler may save attachment-change time on mixed work. Include purchase, subscription, training, maintenance, and compatibility costs alongside the expected operational benefit.
Test the assumptions most likely to change the result
Run a base case and a less favorable case using plausible changes to annual hours, energy cost, repair expenditure, undercarriage life, and resale proceeds. These are planning scenarios, not predictions. Their purpose is to expose how much the purchase depends on favorable conditions.
Start with utilization. Holding capital costs broadly constant, fewer lifetime hours increase their contribution to each operating hour. Then examine application-sensitive costs: undercarriage wear may dominate uncertainty in abrasive work, while energy use may matter more in sustained production.
Identify the break-even point between competing offers. A higher purchase price is justified when the expected savings in energy, maintenance, repairs, and disposal value exceed the additional capital and ownership cost over the planned period. If that result requires unusually high utilization or an aggressive resale estimate, the financial case is fragile.
Where production differs, calculate cost per accepted unit of work = Total relevant cost ÷ Completed, acceptable output. Use comparable excavation conditions and material-volume definitions. This prevents a low hourly rate from masking slow output or costly rework.
Before committing, resolve the assumption with the greatest influence on the decision. That may require a representative operating demonstration, a used-machine inspection, a clearer service agreement, or a firmer disposal arrangement. The strongest purchase case is one that remains economical under a credible operating plan and a realistic allowance for uncertainty.